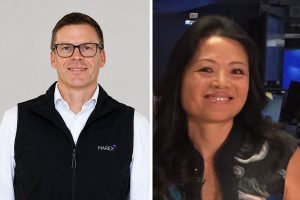
Stephen Hood and Tina Lindstrom
The artificial intelligence infrastructure boom is entering a new phase.
In August, Nvidia announced partnerships with some of the world’s largest investment firms to mobilize more than $500 billion of third-party capital for artificial intelligence infrastructure. Industry estimates now put 2026 capital spending by the world’s largest cloud providers at close to $900 billion, and in the weeks ahead, CME Group is planning to launch futures tied to the rental cost of Nvidia H100 and B200 GPUs.
Taken together, these developments reveal that computational power is emerging as an asset class.
Every new asset class starts with the same basic ingredients: something valuable, something volatile and a market still figuring out how to price the risk. Electricity went through it. Bitcoin went through it. Now it is compute’s turn.
The extraordinary sums being committed to AI infrastructure are creating equally significant financial exposures. If your business depends on GPU processing power, fluctuations in the cost of compute are no longer simply an IT budgeting issue. They are an economic risk.
With the emergence of compute futures, companies will have a way to manage that exposure, just as electricity futures allow utilities and industrial users to manage power prices.
From Infrastructure to Financial Market
Markets tend to develop financial infrastructure around resources that become economically important, scarce and volatile. Oil became financialized as the global economy became increasingly dependent on it. Electricity markets developed sophisticated hedging instruments as deregulation changed the power industry. More recently, digital assets moved from largely unregulated spot trading toward institutional futures and options markets.
Compute appears to be following a similar path—and quickly.
Don Wilson, founder of trading house DRW, also helped establish Silicon Data and establish its GPU benchmarks, creating reference prices for a market that historically lacked transparent, standardized pricing. CME is now preparing to launch futures based on Silicon Data’s H100 and B200 rental indices. ICE has also announced plans for compute futures tied to an energy-normalized index.
Not only is this competition healthy, it is evidence that the market is beginning to take compute price risk seriously.
But creating a futures contract is only one step in building a functioning market. Participants also need reliable reference prices, liquidity and the ability to transfer risk efficiently. Market makers help connect participants looking to hedge with those willing to take the other side, supporting liquidity and price discovery as markets develop.
At Marex, we intend to both clear and make markets in compute products as this market develops. Our role is not to predict which contract, benchmark, or venue ultimately wins, but to provide the liquidity, market access, and risk infrastructure that enable institutional clients to participate.
That does not require taking a long-term, directional view on the price of compute. It requires understanding the underlying exposure, pricing the risk, and helping clients manage it while the market determines where liquidity develops.
The Market Still Has to Mature
Compute futures are not a finished product. Two issues in particular will need to evolve as the market matures.
The first is concentration. The initial CME contracts are tied to Nvidia’s H100 and B200 chips, reflecting Nvidia’s dominant position in the AI ecosystem today. But hyperscalers are developing proprietary chips, competitors are investing heavily and new generations of GPUs are arriving rapidly. As the hardware market diversifies, benchmarks and derivatives will have to evolve with it.
The second is specificity. A specific GPU hour is not necessarily interchangeable with every other GPU hour. Economics can vary depending on hardware, location, energy costs, connectivity and availability.
That creates a challenge that is familiar in commodity markets: the exposure a participant wants to hedge may not perfectly match the most liquid financial instrument available. A company may have exposure to a particular GPU, location, contract or delivery period while the benchmark references something slightly different.
Managing that mismatch—known as basis risk—will be an important challenge as the market develops.
Mature commodity markets have learned to price these kinds of differences. Electricity provides a useful analogy: power is power, but its value can differ dramatically depending on where and when it is delivered. Of note, commodity market makers routinely manage exposures across physical and financial markets even when the traded instrument does not perfectly replicate the underlying risk.
Compute will require the same discipline. These limitations are not reasons to stay on the sidelines, but reminders that disciplined risk management matters from the outset. Historical data will initially be limited, benchmarks will evolve and liquidity may develop unevenly across products and maturities. That makes rigorous stress testing, established risk models and careful expansion of access, particularly important.
The objective is not simply to be early. It is to help build a market that can withstand volatility as participation grows.
The Next Market We Learn to Hedge
Hundreds of billions of dollars are flowing into GPUs, data centers, power generation and the infrastructure required to support AI. Nvidia is helping create financing structures to fund this buildout. Technology companies are racing to secure capacity, and power markets are being reshaped by data-center demand.
Yet one of the fundamental inputs underpinning this investment—the price of compute itself—has remained comparatively difficult to hedge. That is unlikely to last.
As AI becomes embedded across the global economy, compute is becoming an input cost in its own right. Companies will increasingly need to know not only how much compute they will require, but what it will cost them in six months or a year down the road.
Once businesses begin asking that question, derivatives markets tend not to be far behind.
The first contracts will not be perfect. Benchmarks will compete, liquidity will build unevenly and new products will emerge. The market will ultimately decide which contracts and venues succeed.
The important development is that compute is crossing the line from a technology expense into something that can be benchmarked, priced, traded and hedged. The institutions that provide the liquidity and infrastructure around it—carefully, transparently and with disciplined risk management—will help determine how quickly this new market matures.
Stephen Hood is head of clearing, Americas, at Marex.
Tina Lindstrom is head of oil derivatives trading at Marex.
This feature is to provide general information only, does not constitute legal or tax advice, and cannot be used or substituted for legal or tax advice. Any opinions of the authors do not necessarily reflect the stance of ISS STOXX or its affiliates.
Tags: Artificial Intelligence, benchmarks, CME Group, Commodities, Futures, Hedging, Intercontinental Exchange, microchips, Risk